Everybody is talking about interest rates. At the coffee shop, in my DMs, at the closing table. "Rates are too high. I'm going to wait." I get it. Nobody wants a bigger monthly payment than they have to have.
But here's what almost nobody is saying out loud: while everyone is staring at the rate, the market quietly handed buyers the upper hand.
The number nobody is talking about
Right now there are 4,379 homes for sale. That's not a typo, and it's not a small thing. When there are that many choices on the table, sellers have to compete for you. Not the other way around.
Remember 2021 and 2022? Bidding wars. Waived inspections. Offers way over asking just to get a callback. Buyers were basically begging.
Today, buyers get to ask for things again:
- Price reductions
- Seller-paid closing costs
- Repairs after the inspection
- Seller-paid rate buydowns
- Time to actually think about a decision without ten other offers breathing down your neck
That's leverage. And leverage has an expiration date.
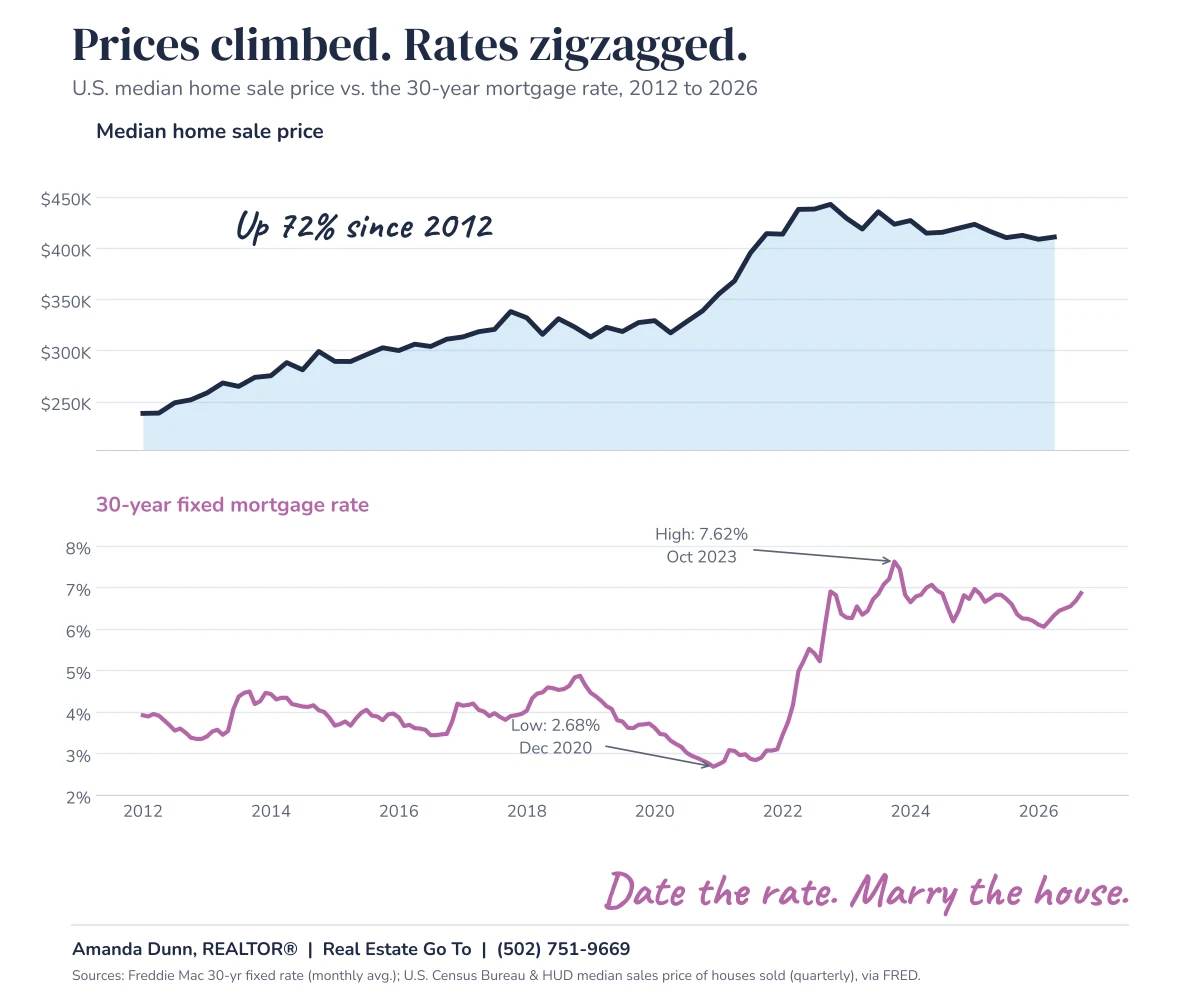
What happens when rates drop
Here's the pattern I've watched play out again and again. Rates dip, even a little, and every buyer who's been sitting on the sidelines jumps back in at the same time.
Suddenly those 4,379 homes don't feel like so many. Showings stack up. Multiple offers come back. Prices climb. And that negotiating power buyers have today? Gone.
So the people "waiting for rates to come down" are really waiting to compete with everyone else who had the exact same idea. They might get a lower rate, but they'll likely pay a higher price, with fewer concessions and a lot less room to say no.
Date the rate, marry the house (I hate this saying, but man is it true)
This is where we flip the script.
Your interest rate isn't permanent. Your purchase price is.
A rate can change down the road through a refinance. The price you pay is locked in forever. It's what your loan is built on and the starting line for every dollar of equity you'll ever have in that home.
So instead of waiting for the "perfect" rate, the smart play looks like this:
- Buy while you have the leverage. Negotiate the price, the repairs, the closing costs. Make the seller work for you.
- Live in it and build equity. Every payment and every bit of appreciation works in your favor, not your landlord's.
- When rates come down, talk to your lender about refinancing. You keep the great price you negotiated and potentially lower your payment too. You can always change an interest rate. You can never change the price you bought your home at!
Let's put it side by side
Here's a simple example, just to show the idea (these are made-up numbers, not a quote):
Buyer A buys today. There's plenty of inventory, so she negotiates $10,000 off the list price and gets the seller to cover about $5,000 in closing costs. She locks in a 7.2% interest rate and pays $280,000. Later, if rates drop, she looks into refinancing at a lower rate and pulling some equity out to update the home, which builds her equity even more.
Buyer B waits for rates to fall, paying $1,300 a month in rent for a year. That's $15,600 gone. When rates finally do drop, so does everyone else who was waiting. He ends up in a multiple-offer situation and pays $295,000 for a similar home, with no concessions.
Even if they end up with similar rates, Buyer A has a lower loan balance, a head start on equity, and she got to live in her home the whole time Buyer B was waiting.
The honest fine print
I'd rather you hear this from me than find out later:
- Nobody can promise rates will drop, or when. Buy a payment you can comfortably afford today, at today's rate. If the numbers only work after a refinance, they don't work.
- Refinancing isn't free. There are closing costs, and you'll need to qualify again with your income, credit, and equity. Ask your lender to walk you through the break-even point.
- This is a strategy, not a guarantee. Every buyer's situation is different, so sit down with a lender and look at your real numbers before you make a move.
So, are you waiting or winning?
The headlines want you focused on the rate. I want you focused on the opportunity. Right now buyers have choices, time, and negotiating power, and that doesn't happen every year.
If you've been sitting on the fence, let's talk about what buying could look like for you. Get pre-approved so you can see your real numbers, or reach out and we'll go find a house worth marrying.